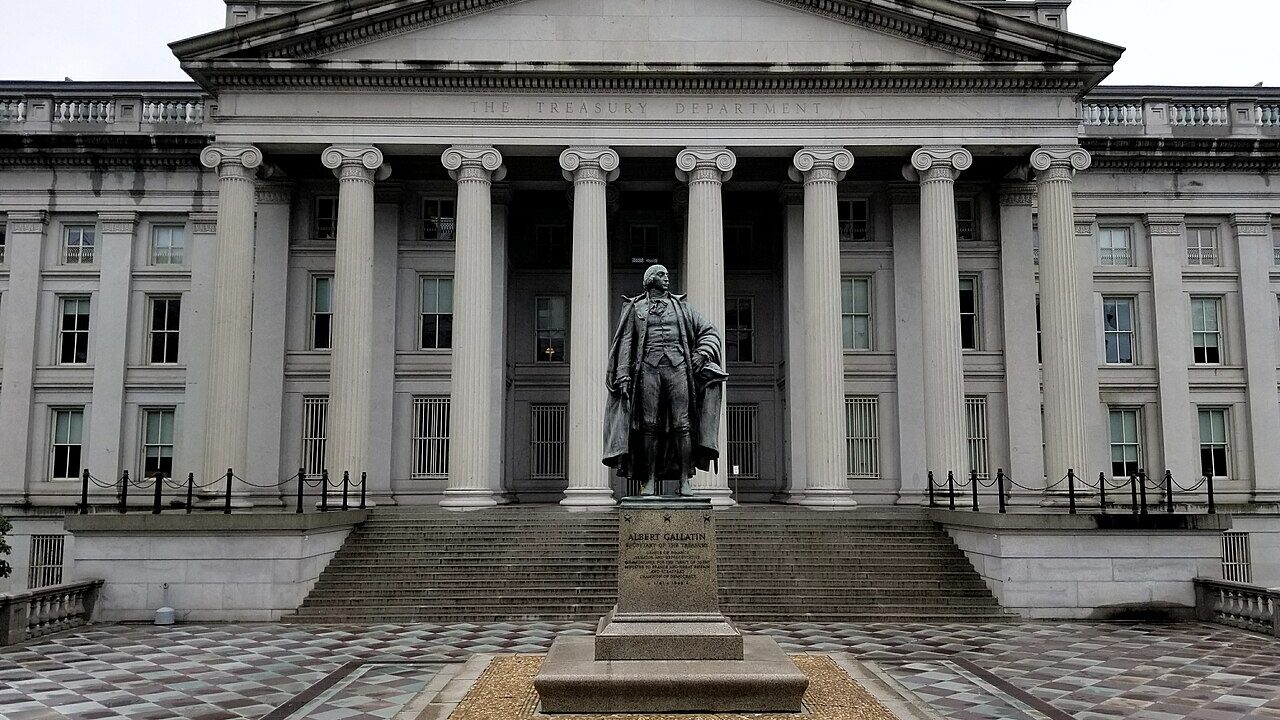
The federal regulator for America’s national banks has published a 47-page report concluding that all nine of the country’s largest banks operated policies allowing them to deny or limit financial services based on customers’ political, religious or social views — or their lawful business activities. The review examined nearly 100,000 complaints and around 420,000 pages of bank documents spanning 2020 to September 2025.
At the centre of the findings were so-called “reputational risk” policies. The Office of the Comptroller of the Currency said these policies required, encouraged or otherwise influenced decisions on whom to serve — yet lacked clear, objective, risk-based standards. In practice, investigators found, that vagueness became the machinery of debanking: judgments shaped by a customer’s beliefs or by whether their industry had become politically unfashionable.
The examples name ordinary victims, not abstractions. A payments firm owned by JPMorgan Chase closed merchants’ accounts for selling merchandise promoting President Trump, flagging terms such as “MAGA” and “America First” — without any written standard for when a slogan crossed a line. Wells Fargo pressed a payment processor to drop a religious nonprofit over its views on same-sex marriage. PNC refused credit to a media company linked to Christian conservative donors. The report also acknowledged cases involving Democrat-aligned organisations, and stressed that legitimate closures — for fraud or chronic overdrafts — were commonplace.
The road to the report
The review was ordered under President Trump’s August 2025 executive order guaranteeing fair banking access, and it follows groundwork laid by the states: Tennessee passed a fair-access law in 2024, with Florida and Idaho following, prompting many banks to revise policies in late 2023 and 2024. Comptroller Jonathan V. Gould said the revisions did not go far enough — no bank, he said, had fully and publicly acknowledged what he called the weaponisation of finance against hardworking Americans. “Fair access to financial services is not a mantra — it is a mandate,” he said.
What it means for customers
For ordinary account-holders, the significance is that the regulator is now watching. The OCC is weighing further action, and the Consumer Financial Protection Bureau has opened its own investigation into consumer harm. Customers who believe they were denied services over their beliefs can complain to the OCC’s customer assistance unit — the same channel that produced the 100,000 complaints behind the report.
The industries flagged — oil and gas, coal, firearms retailers, detention facilities, tobacco and digital-asset businesses — are lawful parts of the economy that should be judged on risk, the report said, not reputation. The findings landed in a midterm season already marked by disputes over federal power, including a court order halting taxpayer-funded campaign advertising.