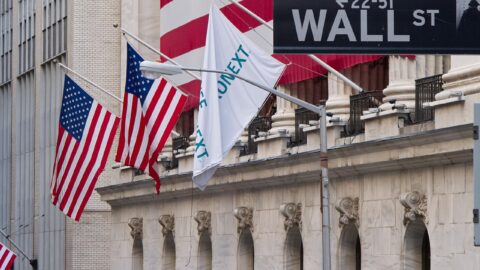
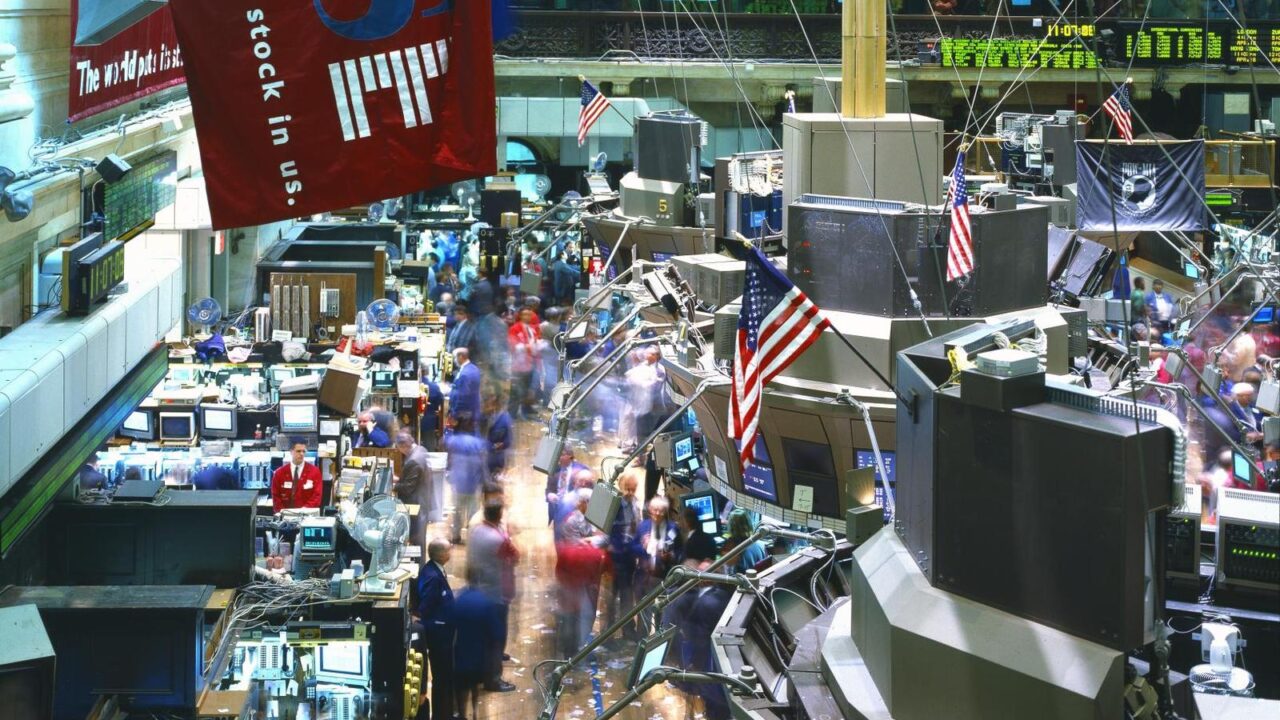
Wall Street suffered its worst day since June on Thursday as the Nasdaq tumbled 2.6 percent, the S&P 500 fell 1.21 percent and the 10-year Treasury yield climbed to 4.96 percent, a toxic combination of falling equities and rising borrowing costs. The selloff was broad, but technology shares bore the brunt as investors reassessed the market’s most crowded trade.
The damage was concentrated in the mega-cap technology stocks that have carried the market for two years. Reports that Calpers, the giant California pension fund, has been trimming its holdings in the so-called Magnificent 7 added to the selling pressure. When the largest institutional investors start reducing exposure to the market’s leaders, smaller holders tend to follow.
Yields bite
The rise in the 10-year yield to 4.96 percent is doing quiet damage across the economy. Higher long-term rates raise mortgage costs, corporate borrowing costs and the discount rate applied to future earnings, which hits growth stocks hardest. The combination of falling stock prices and rising yields is particularly painful for the classic balanced portfolio, which is suffering on both sides at once.
Behind the market moves sits a darker economic backdrop. Brent crude above 114 dollars a barrel is stoking inflation fears, and geopolitical tensions from the Gulf to the Korean Peninsula are keeping risk appetite in check. Markets hate uncertainty, and there is no shortage of it right now.
What comes next
The question for investors is whether Thursday was a healthy correction or the start of something worse. The bull case: earnings remain solid, the economy is still growing, and pullbacks in the mega-caps create buying opportunities. The bear case: valuations were stretched, yields are restrictive, and the institutional selling may have further to run. For more on the forces moving markets, see our earlier coverage of the midterm backdrop investors are watching and the campaign trail developments shaping sentiment. The market data behind today’s moves is updated through the close.